Date:
November 15, 2026
Author:
/
Summary and contents
For a Colorado CollegeInvest 529, check the plan disclosure and your account record for the successor account owner. The successor takes over the owner’s role under the plan’s rules. CollegeInvest’s general FAQ says that if you do not name a successor, the beneficiary becomes owner upon your death. Confirm the specific terms and process for your account, especially if the student is a minor.
- Separate the student from the person in charge
- Check the plan’s default before relying on your will
- Use the provider’s form and confirm acceptance
- Avoid turning an ownership review into an unnecessary transfer
- Keep a one-line record for every education account
- Comparison at a glance
- Visual guide
- Related video
- Frequently asked questions
- Can the student also become the account owner?
- Can I cover separate 529s with one update?
- Can my estate planning attorney change the provider’s record by updating my will?
- Sources and next steps
A grandparent can fund a 529 for a child for years and still leave one question unanswered: who will manage the account if the grandparent dies? The student’s name may be on the statement, but that name alone does not tell you who will make the next withdrawal.
Separate the student from the person in charge
The beneficiary is the student for whom the account is intended. The account owner generally manages withdrawals and other account decisions subject to the plan. The successor owner is the person designated to assume the owner’s responsibilities when the plan’s conditions are met.
These can be three different people. For example, a Greenwood Village grandmother owns a 529 for her granddaughter. She may want the girl’s parent to handle tuition payments if the grandmother dies while the student is still in high school. Reviewing the successor designation is how she checks whether that is what the plan records reflect.
Ask whether your priority is continuity of management, continued funding, or who makes decisions if the student’s education plans change. Those goals help you choose a person who understands when and how to use the money.
Check the plan’s default before relying on your will
The CollegeInvest FAQ describes its default when no successor is named: the beneficiary becomes account owner upon the owner’s death. The plan disclosure and account registration govern the details. Other providers may use a different default, so do not carry this assumption over to a 529 held elsewhere.
If the beneficiary is a minor, ask how the plan handles ownership and decisions until an adult can properly act. Ask about custodial registrations, an unavailable successor, and any life events other than death that may be covered. A generic form or a line in a will is no substitute for checking the plan’s accepted records.
For a family with a will or trust that names one person to manage an inheritance and an account record that identifies someone else, map both jobs. People may be able to serve in both roles, but the source of their authority differs.
Use the provider’s form and confirm acceptance
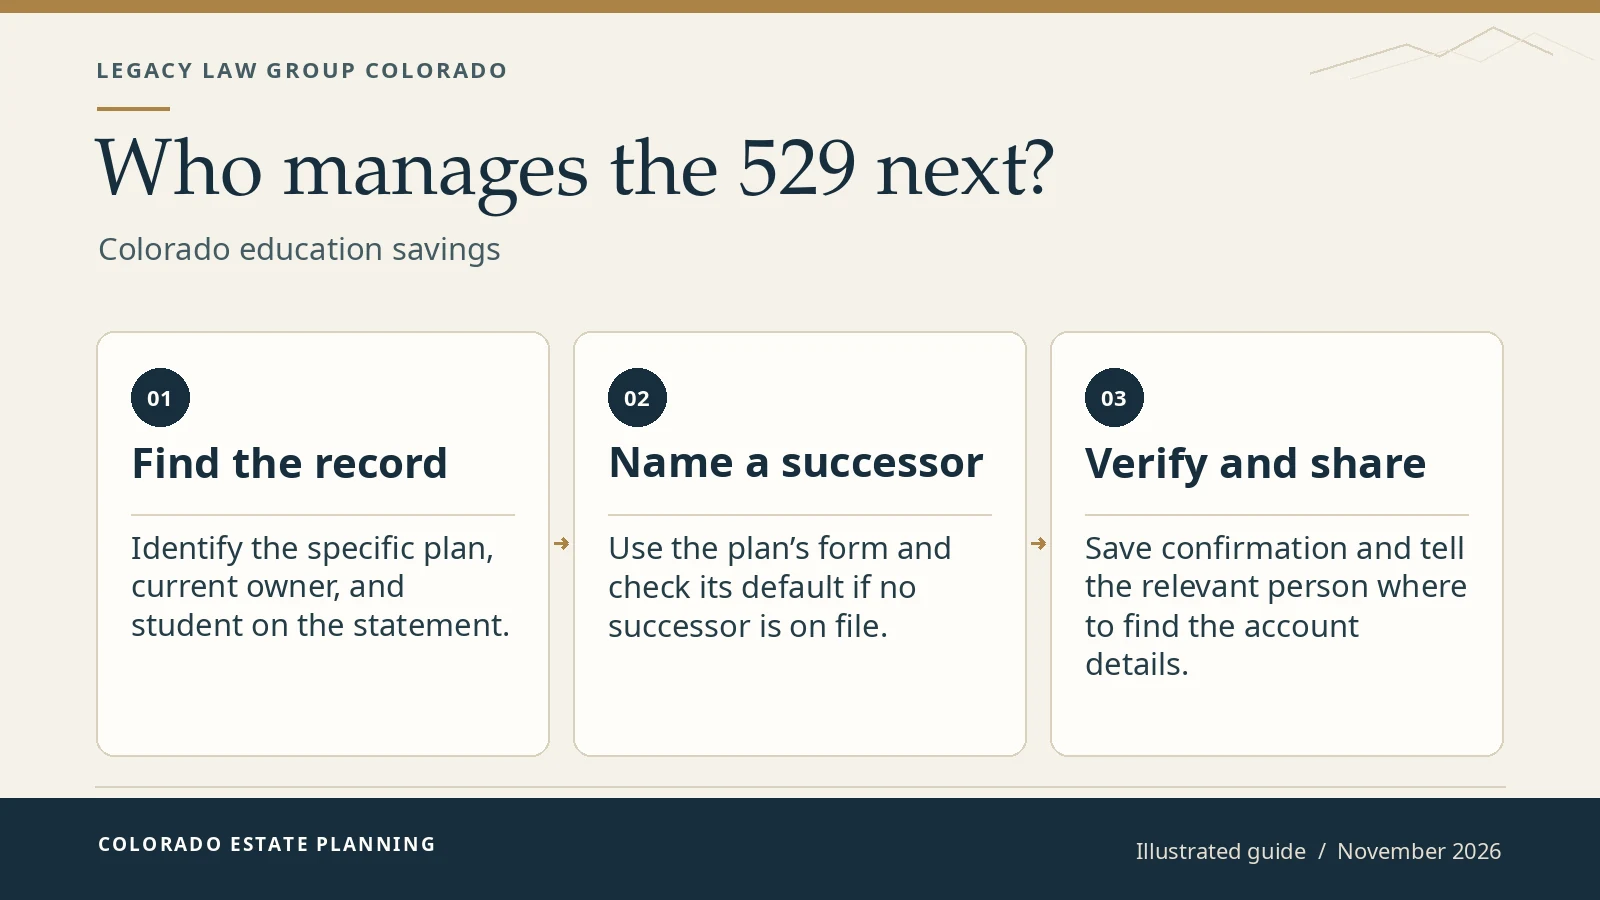
Find the provider and exact plan name on the latest account statement. If you hold a CollegeInvest Direct Portfolio account, open the Direct Portfolio forms page. CollegeInvest also provides separate resources for Stable Value Plus, Smart Choice, and Scholars Choice. Use the instructions for the actual plan.
Request written confirmation showing the successor on the record. Check the spelling and make sure the provider processed the change for each account. Store the confirmation where the appropriate person can find it, with the plan’s contact details and the last four digits of the account.
After a death, contact the plan for its transfer procedure. For Direct Portfolio, the plan disclosure describes a written request, enrollment application, and certified death certificate for a successor transfer. Ask what the plan accepts for your current registration and whether a minor or a custodial account requires different paperwork. A successor should use the provider’s process rather than logging in as the deceased owner or assuming that a submitted change is already effective.
Avoid turning an ownership review into an unnecessary transfer
Naming a future successor is different from replacing the current owner, changing the student, moving the assets to another plan, or taking a distribution now. Each action can have different consequences. The IRS 529 guide outlines federal rules that can affect distributions, beneficiary changes, and rollovers.
If you are considering an actual transfer, ask the plan and your tax adviser to review the account type, the current and proposed beneficiaries, prior contributions, and any state tax consequences. Do not assume that a family relationship or a trust designation makes every change tax neutral.
Talk to the proposed successor about your goals. A short note can explain which education costs you intended to support, whom to involve in decisions, and when to ask for advice. Keep the note separate from provider records and legal instructions.
Keep a one-line record for every education account
For each account, record the provider, owner, student, successor, confirmation date, and the location of the latest statement. If you cannot fill in the successor or confirmation date, make it a follow-up item. Repeat the review after changing providers, losing a named successor, or adding a new account for another child.
Compare that list with your will, trust, and any plans for a minor’s inheritance. Legacy’s Colorado estate planning checklist can help organize the wider review. The firm’s guide to estate planning for parents with minor children explains other roles families may need to plan for.
Comparison at a glance
| Role | Question to ask | Record to confirm |
|---|---|---|
| Account owner | Who manages the account today? | Current account registration |
| Beneficiary | Whose education is it intended to support? | Beneficiary name on the plan record |
| Successor owner | Who will manage it after the owner’s death? | Accepted successor designation and plan rules |
Visual guide
Related video
This related Legacy Law Group Colorado video provides background. Use the written guide for the specific procedures and rules discussed here.
Watch on YouTube: The Importance of Estate Planning When You Have Minor Children.
Frequently asked questions
Can the student also become the account owner?
That may happen under the plan’s rules. CollegeInvest describes this as its general default at death if no successor is named. Confirm the plan terms and procedure if the student is a minor.
Can I cover separate 529s with one update?
Do not assume so. Confirm the current designation and accepted changes account by account, particularly if the plans have different providers.
Can my estate planning attorney change the provider’s record by updating my will?
Do not rely on a will update alone. Ask separately about the plan’s accepted designation and how it coordinates with your estate documents.
Sources and next steps
- CollegeInvest: 529 FAQs and account succession
- CollegeInvest: enrollment checklist and successor owner
- CollegeInvest Direct Portfolio: forms and account changes
- IRS: 529 questions and answers
- CollegeInvest Direct Portfolio: plan disclosure and succession process
Sources checked November 15, 2026. This article provides general information about Colorado planning. The details of your documents and circumstances matter.
For help reviewing your estate plan, contact Legacy Law Group Colorado.